On Asymmetric Bets
Most of what looks like luck in my business is a bet that cost almost nothing and paid off big. Not once. Over and over, on purpose. That pattern has a name, and once you see it you can't stop making them.
An asymmetric bet is a small, calculated risk with a large potential upside. Small downside, capped and known. Big upside, uncapped. You lose a little when you're wrong, you win a lot when you're right, and because the losses are tiny you get to be wrong many times before one win pays for all of them.
That is not gambling. Let me be precise about why, because the difference is the whole post.
Risk versus gamble
Robert Greene draws the line cleanly. A gamble is when you bet without understanding the odds or the stakes, and you're hoping. A risk is when you've studied the situation, you know what you can lose, you've sized the bet so losing doesn't kill you, and you act. The gambler and the risk-taker can be at the same table making the same move. One of them knows what he's doing.
Ray Dalio gets at the same thing from a different angle, and he's the one who taught me to copy like a builder. Not copy the output. Copy the machine. He treats decisions as a system you can study, write down, test, and improve, so that every bet makes the next one smarter. When I read him I stopped thinking about individual wins and started thinking about the process that produces them. That shift is the entire difference between a founder who got lucky once and a founder who keeps getting "lucky."
So: an asymmetric bet is a risk, not a gamble, because you know the downside, you've capped it, and you've engineered the odds in your favor by making many of them.
Forty doors, one client
Here's what it looked like at the very beginning, before any of this was a company.
I cold called. I knocked on doors. Not because I enjoy it, I'd rather be alone in a room building, but because the math was obvious once I ran it. Each call costs a few minutes and a little dignity. The downside of a no is nothing. It doesn't compound, nobody remembers, and I'm no worse off than before I dialed. The upside of a yes is a client, which can mean years of revenue and a referral chain I can't even see yet.
Most of them said no. Of course they did. But one of those early conversations turned into a big client, and that client turned into the case study that landed the next three. Thirty-nine rejections and one yes is not a bad week. It's a great one, if the yes is big enough, and in business the yes is usually big enough.
People who won't make this bet are protecting themselves from a downside that doesn't exist. The rejection is free. They're treating it like it costs something.
Twelve ads, twenty bucks each
Same math, different arena.
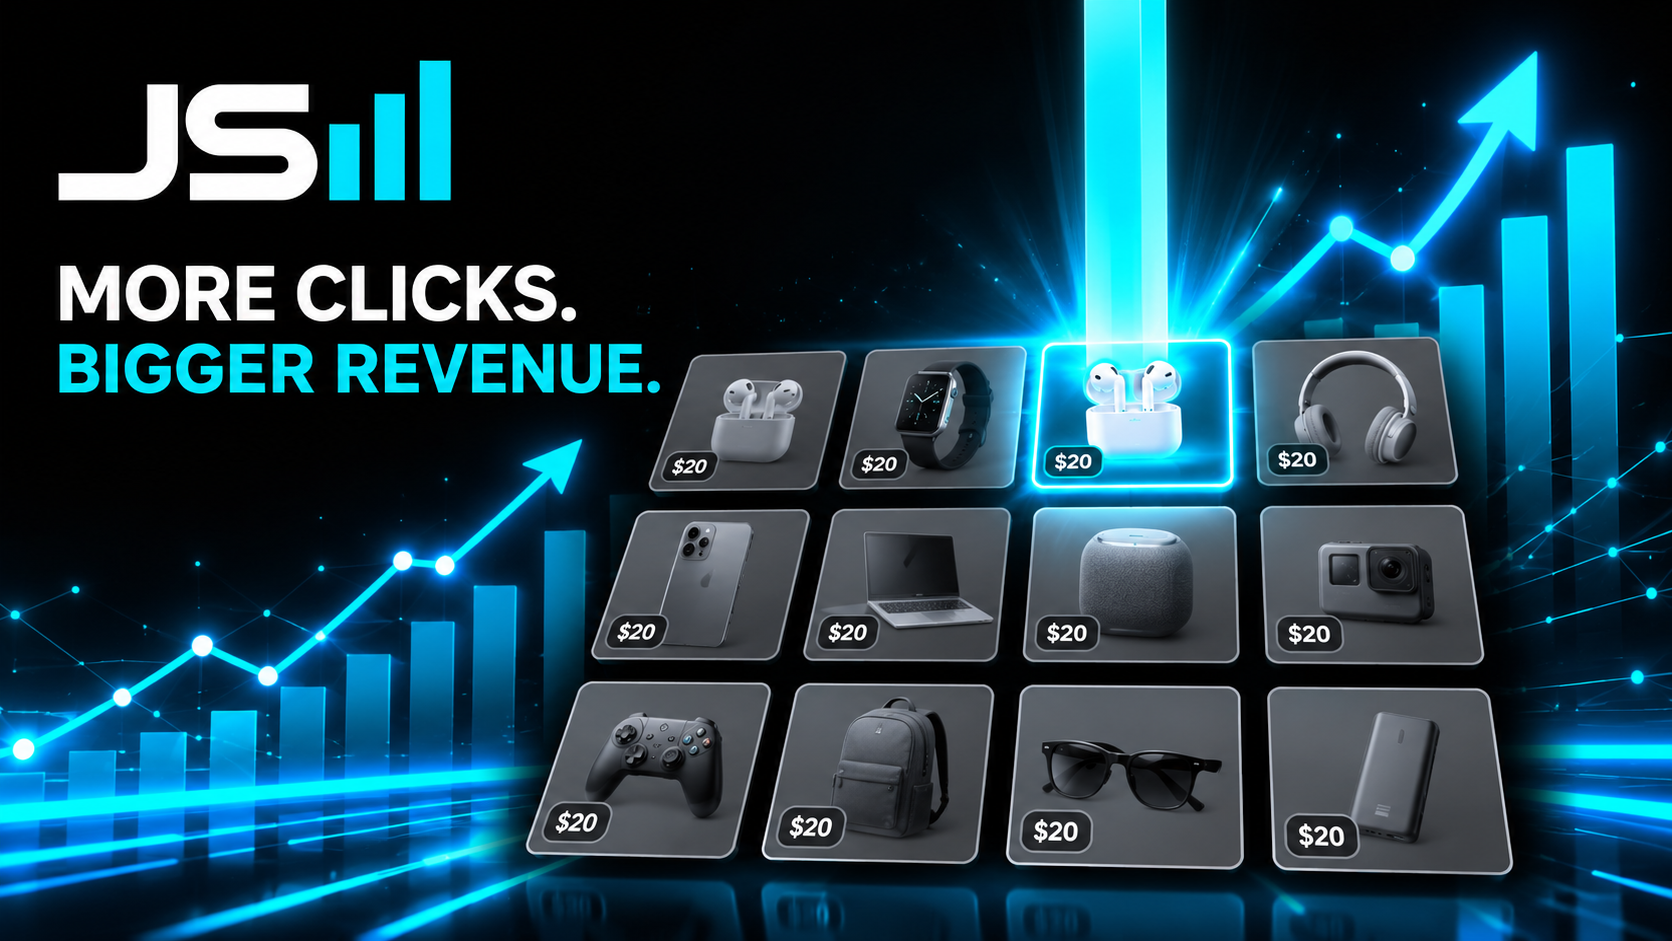
When we run ads for a client, we don't launch one perfect ad. We launch a dozen cheap ones. Twenty dollars behind each, a few days, let the numbers talk. Eleven of them do nothing and we turn them off. We're out a couple hundred bucks. One of them hits, and that one gets the real budget, and that one is how a cabinet shop goes from under a million to $1.3 million.
The gambler's version of this is picking the ad you like best and putting the whole budget on it. Feels confident. It's a coin flip with your month's spend on it. The asymmetric version is twelve tiny bets, most of which you expect to lose, structured so that the one winner pays for everything and then some. You're not predicting the winner. You're buying the right to find it cheaply.
Entrepreneurship is just this, repeated
Zoom out and the whole job is asymmetric bets.
Starting the company was one. The downside was a year of my life and some savings, real but survivable. The upside was, well, everything I have now. Drawing six boxes on a piece of paper and building the ugly version was one. Cost me a weekend. Became business number four. Giving software away free to build relationships, which I've written about, is one. Costs me almost nothing per account. Occasionally turns into a website build or a retainer.
Even building a news site nobody asked for was one. A weekend of work, a cron job, and if it does nothing I've lost a weekend. If it compounds into SEO and distribution for years, I got that for the price of a weekend.
The founders who make it aren't the ones with the best single idea. They're the ones who've structured their life so they can take a lot of cheap shots at big targets. Small downside, uncapped upside, many attempts. The returns are outsized because the math is outsized, not because they're smarter.
No shame in the duct tape
Here's the part people get wrong, and it's why they never make the first bet.
An asymmetric bet only works if the downside is actually small, and the thing that makes the downside small is that you didn't over-invest before you knew anything. The first product is held together with duct tape. The first cold call script is bad. The first ad is ugly. That's not a failure of standards. That's the bet being sized correctly.
My first product ran on a HighLevel form, a Zapier endpoint, and middleware I can no longer explain. I've said that out loud on this blog and I'll say it again, because there is no shame in it. That duct-tape version is how I learned sales, marketing, and product at the same time, on real customers, for almost no money. If I'd waited until it was polished, I'd have spent six months building something nobody wanted, and that's a big bet with a small upside, which is the exact opposite of what you want.
Scrappy isn't a phase you apologize for. It's the mechanism. The duct tape is what keeps the downside small enough that you can afford to be wrong.
How to actually do this
Three rules I run by.
- Know the downside before you make the move. Write it down. If "worst case" isn't a number you can say out loud and survive, it's not asymmetric, it's a gamble. Shrink it until it is.
- Size for many attempts, not one. You're not trying to be right. You're trying to find the thing that's right, cheaply, by being wrong a lot. Budget for the whole batch.
- Let the winners get the real money. The point of the small bets is to find the one that deserves a big one. When it shows up, don't keep it small out of habit. That's when you burn the boats.
The takeaway
Asymmetric bets are small, calculated risks with large potential upside. Not gambles, because you know what you can lose and you've made sure it's survivable. Cold calls, cheap ad tests, ugly first products, weekend projects. Lots of them. Most lose a little. One wins big, and then you do it again.
That's not luck. It's the only strategy I've ever seen work for someone starting with nothing, and the first bet is always cheaper than you think.
Want help finding the bet?
Diagnosing the cheap test with the big upside is most of what I do with clients at HyppoAI.